<?xml version="1.0" encoding="utf-8"?><feed xmlns="http://www.w3.org/2005/Atom" ><generator uri="https://jekyllrb.com/" version="3.10.0">Jekyll</generator><link href="https://alexisakira.github.io/feed.xml" rel="self" type="application/atom+xml" /><link href="https://alexisakira.github.io/" rel="alternate" type="text/html" /><updated>2026-09-07T06:42:32-07:00</updated><id>https://alexisakira.github.io/feed.xml</id><title type="html">Alexis Akira Toda</title><subtitle>Personal academic website of Alexis Akira Toda, Professor of Economics at Emory University, featuring research in macro-finance, asset price bubbles, power laws, and computational economics.</subtitle><author><name>Alexis Akira Toda</name><email>alexis.akira.toda(at)emory.edu</email></author><entry><title type="html">Econ Journal Watch now officially accepts LaTeX submissions</title><link href="https://alexisakira.github.io/posts/2026/08/blog-post-30/" rel="alternate" type="text/html" title="Econ Journal Watch now officially accepts LaTeX submissions" /><published>2026-08-30T00:00:00-07:00</published><updated>2026-08-30T00:00:00-07:00</updated><id>https://alexisakira.github.io/posts/2026/08/blog-post</id><content type="html" xml:base="https://alexisakira.github.io/posts/2026/08/blog-post-30/"><![CDATA[<p>Good news. <a href="https://econjwatch.org/"><em>Econ Journal Watch</em></a> now officially accepts LaTeX submissions. Its <a href="https://econjwatch.org/call-for-papers/instructions-for-authors-style-guide">Instructions for Authors &amp; Style Guide</a> states that authors may submit manuscripts in LaTeX using the downloadable template.</p>

<p>EJW has long been one of my favorite journals, but it had not accepted LaTeX submissions. As I wrote in a <a href="/posts/2025/09/blog-post-30/">previous post</a>, I had been urging the editorial board to make the transition. In 2025, EJW began publishing papers typeset in LaTeX, but the author-facing submission process had not yet been formally established.</p>

<p>I volunteered to develop the EJW LaTeX class file and presented it in my talk, <a href="/talks/">“A Public LaTeX Template for Econ Journal Watch”</a>, at the online EJW Powwow on August 23. The class file is now accepted by EJW and available through its official author instructions. It is also available as an <a href="https://www.overleaf.com/latex/templates/manuscript-template-for-econ-journal-watch-ejw/xxvbryjywqhh">Overleaf template</a>, so authors can begin writing in the browser without any local setup.</p>

<p>I am proud to have played a part in this development. I hope that the template makes it easier for authors to submit clear, consistently formatted papers to a journal that I greatly admire.</p>]]></content><author><name>Alexis Akira Toda</name><email>alexis.akira.toda(at)emory.edu</email></author><category term="research" /><summary type="html"><![CDATA[Good news. Econ Journal Watch now officially accepts LaTeX submissions. Its Instructions for Authors &amp; Style Guide states that authors may submit manuscripts in LaTeX using the downloadable template.]]></summary></entry><entry><title type="html">A classical-type theorem about external squares on two sides of a triangle</title><link href="https://alexisakira.github.io/posts/2026/07/blog-post-22/" rel="alternate" type="text/html" title="A classical-type theorem about external squares on two sides of a triangle" /><published>2026-07-22T00:00:00-07:00</published><updated>2026-07-22T00:00:00-07:00</updated><id>https://alexisakira.github.io/posts/2026/07/blog-post</id><content type="html" xml:base="https://alexisakira.github.io/posts/2026/07/blog-post-22/"><![CDATA[<p>I have been amazed by ChatGPT Pro recently, and here is another episode.</p>

<p>In 1994, when I was 14 years old and playing around with Pythagorean theorem-like figures, I discovered the following fact:</p>

<blockquote>
  <p>Let ABPQ and ACRS be squares erected externally on two sides of a triangle ABC. Then the lines CP and BR meet on the altitude from A to BC.</p>
</blockquote>

<p>At the time, I was unable to prove the statement, but during high school I proved it analytically by setting coordinates (A(0,a)), (B(-b,0)), (C(c,0)).</p>

<p>Yesterday, it occurred to me to ask ChatGPT Pro to find an elementary proof and write a paper. With a single <a href="https://chatgpt.com/share/6a60f8df-58c4-83ea-be5f-533e7d4c71c7">prompt</a>, it did an amazing job. However, when I challenged it to do a literature review, it found that the result had already been published in an 1817 paper by Vecten. So of course, I’m not going to write a paper about this.</p>]]></content><author><name>Alexis Akira Toda</name><email>alexis.akira.toda(at)emory.edu</email></author><category term="research" /><summary type="html"><![CDATA[I have been amazed by ChatGPT Pro recently, and here is another episode.]]></summary></entry><entry xml:lang="ja-JP"><title type="html">さらばSBI新生銀行、さらばJALカード</title><link href="https://alexisakira.github.io/posts/2026/06/blog-post-22/" rel="alternate" type="text/html" title="さらばSBI新生銀行、さらばJALカード" /><published>2026-06-22T00:00:00-07:00</published><updated>2026-06-22T00:00:00-07:00</updated><id>https://alexisakira.github.io/posts/2026/06/blog-post</id><content type="html" xml:base="https://alexisakira.github.io/posts/2026/06/blog-post-22/"><![CDATA[<p>この度、来日ついでに20年以上保有してきたSBI新生銀行の口座とJALカードのクレジットカードを解約した。</p>

<p>SBI新生銀行は2001年からオンラインバンキングや提携ATM利用手数料無料など、当時としては画期的なサービスを提供していたので長らく使ってきた。ただ、ここ数年、振り込むときに携帯電話を使った認証を必要とするようになって使い勝手が悪くなった。これまではアメリカのスマホでもthird partyを使って認証コードが受け取れたのだが、今月末から日本の携帯電話番号が必要になり、もはや資金を受け取るか日本のATMで下ろすかしかできなくなってしまったので、口座閉鎖を決断した。今後は、円決済はSMBC信託銀行一本で行くことになる。SMBC信託銀行（旧シティバンク）は国内銀行では珍しく、非居住者にも口座維持を認めており、（滅多に使わないけれども）国内・海外送金がオンラインで完結できる。</p>

<p>SBI新生銀行の口座を閉鎖すると同時にJALカードも解約した。2006年頃、JALに乗りまくったときにJALグローバルクラブの入会資格を得て、資格維持のためにカードを作った。これはJRのViewcard Suicaと連動しているものだったのでオートチャージができてそれなりに便利だったのだが、日本に来たときにしか使わないのに年会費1万円以上を払うのはあまり合理的ではなかった。また、Viewcardのウェブサイトの使い勝手が悪いことやカードの還元率が魅力的でないことも不満だった。極めつけは、引き落とし口座をSMBC信託銀行に変更しようとしたら、指定金融機関でなかったのでできないということだった。最近、JALマイレージバンクの海外会員だとクレジットカードがなくても年間2000マイル引き落としでJALグローバルクラブの会員資格が維持できることが判明したので、こちらに再加入する予定である。ところで、JALのマイルは家族で通算できる上に、毎年乗らなくても2000マイル引き落としだけでJALグローバルクラブの資格が維持できるので、かなり割が良い気がする。</p>

<p>今後は、日本での現金の出し入れやセミナー時の交通費・謝金などの受け取りにはSMBC信託銀行を使い、日常の決済は使える限りアメリカのクレジットカードで行くことにする。口座が減って、ログインの仕方やポイントの有効期限などの心配事が減るのはよいことだ。</p>]]></content><author><name>Alexis Akira Toda</name><email>alexis.akira.toda(at)emory.edu</email></author><category term="credit card" /><category term="personal finance" /><category term="travel" /><summary type="html"><![CDATA[この度、来日ついでに20年以上保有してきたSBI新生銀行の口座とJALカードのクレジットカードを解約した。]]></summary></entry><entry><title type="html">Migration to Japan works only for lower-middle-class Americans</title><link href="https://alexisakira.github.io/posts/2026/06/blog-post-07/" rel="alternate" type="text/html" title="Migration to Japan works only for lower-middle-class Americans" /><published>2026-06-07T00:00:00-07:00</published><updated>2026-06-07T00:00:00-07:00</updated><id>https://alexisakira.github.io/posts/2026/06/blog-post</id><content type="html" xml:base="https://alexisakira.github.io/posts/2026/06/blog-post-07/"><![CDATA[<p>I often see posts about Americans moving to Japan for affordability and other reasons, such as food and culture. It is true that life in Japan is quite affordable these days, perhaps due to the weak yen and over three decades of economic stagnation. I sometimes dream about living in Japan after I retire.</p>

<p>However, after doing some math, I have to conclude that migrating to Japan works only for lower-middle-class Americans.</p>

<p>The reason is taxes. As in many countries, Japan has a progressive income tax system, with a <a href="https://www.nta.go.jp/taxes/shiraberu/taxanswer/shotoku/2260.htm">maximum marginal tax rate of 45%</a>. This is not just significantly higher than the United States’ <a href="https://www.irs.gov/filing/federal-income-tax-rates-and-brackets">maximum marginal tax rate of 37%</a>. The maximum tax rate of 45% kicks in at a taxable income of 40,000,000 yen (about 250,000 dollars), which is basically a middle-class income in the United States.</p>

<p>Let’s also not forget that, in addition to the national income tax, there is a flat-rate 10% resident (municipal) tax, so the maximum income tax burden is really 55%.</p>

<p>When you spend money using your after-tax income, there is also a 10% consumption (value added) tax (8% for food).</p>

<p>Japan also has a high inheritance tax: the maximum tax rate is 55%, which applies to estates exceeding 600,000,000 yen (about 3.75 million dollars). And you can’t avoid inheritance tax just by moving abroad: for Japanese citizens, the inheritance tax applies up to 10 years after leaving the country.</p>

<p>But perhaps the most significant impediment to living in Japan (establishing residency) is the annual requirement to report foreign assets to the National Tax Agency. In addition, capital gains and dividends from foreign assets are taxed as ordinary income. Of course, Japan does not recognize Roth IRAs in the United States, so even incomes within Roth IRAs are taxed.</p>

<p>These rules mean that any middle-class (or above) American moving to Japan will face a significant tax and administrative burden. If you have some assets and still want to move to Japan, I suggest converting all your assets into a portfolio of stocks that do not pay dividends (such as Berkshire Hathaway and many tech stocks) and that you do not sell stocks while you live in Japan.</p>]]></content><author><name>Alexis Akira Toda</name><email>alexis.akira.toda(at)emory.edu</email></author><category term="personal finance" /><category term="tax" /><summary type="html"><![CDATA[I often see posts about Americans moving to Japan for affordability and other reasons, such as food and culture. It is true that life in Japan is quite affordable these days, perhaps due to the weak yen and over three decades of economic stagnation. I sometimes dream about living in Japan after I retire.]]></summary></entry><entry xml:lang="ja-JP"><title type="html">住所と相続税</title><link href="https://alexisakira.github.io/posts/2026/05/blog-post-25/" rel="alternate" type="text/html" title="住所と相続税" /><published>2026-05-25T00:00:00-07:00</published><updated>2026-05-25T00:00:00-07:00</updated><id>https://alexisakira.github.io/posts/2026/05/blog-post</id><content type="html" xml:base="https://alexisakira.github.io/posts/2026/05/blog-post-25/"><![CDATA[<p>最近、Geminiに「引退後はどこに住んだらいいか、税制の観点から説明してほしい」みたいなことを聞いたら、目から鱗の情報を教えてくれた。</p>

<p>日本は経済停滞や円安の影響もあって生活コストは低いけれども、相続税が半端なく高いとのこと。例えば、<a href="https://www.nta.go.jp/taxes/shiraberu/taxanswer/sozoku/4155.htm">国税庁</a>によると、相続額が6億円を超えると限界税率が55%で、控除額はたったの7200万円（基礎控除を含めると1億円強になるが）。しかも、住民票を抜いて非居住者になったとしても、10年間は相続税の納税義務があるとのこと。</p>

<p>これを知って老後の計画が根本的に変わってしまった。ラーメン一杯3000円するような物価の高いアメリカに住んでいると自分は決して富裕層には感じないけれど、日本だったら相続税の心配をするぐらいの資産は持っている。日本は温泉とか食べ物が好きだし、医療サービスの質が高いので、長期的に住みたいと思ったけど、住民票を入れた瞬間に国税庁に追い回されるのはたまったものではない。アメリカの税制だと、夫婦の場合2800万ドル、今の為替レートで45億円ぐらいまでは遺産税が非課税だから、アメリカに居住するかぎり相続税のことは心配しなくていい。今後一生、たぶん日本に住民票を入れることはないだろうなと思った。</p>

<p>Geminiが言うには、老後は州税の低い（またはゼロ）のアメリカの州を生活の拠点にしつつ、日本の居住者とみなされない範囲内で数ヶ月単位で旅行するのが最適だそうだ。昔読んだ小説「<a href="https://www.gentosha.co.jp/book/detail/9784344010116/">永遠の旅行者</a>」を思い出す。</p>]]></content><author><name>Alexis Akira Toda</name><email>alexis.akira.toda(at)emory.edu</email></author><category term="personal finance" /><category term="tax" /><summary type="html"><![CDATA[最近、Geminiに「引退後はどこに住んだらいいか、税制の観点から説明してほしい」みたいなことを聞いたら、目から鱗の情報を教えてくれた。]]></summary></entry><entry><title type="html">Capital One Quicksilver 0% intro APR (4)</title><link href="https://alexisakira.github.io/posts/2026/04/blog-post-20/" rel="alternate" type="text/html" title="Capital One Quicksilver 0% intro APR (4)" /><published>2026-04-20T00:00:00-07:00</published><updated>2026-04-20T00:00:00-07:00</updated><id>https://alexisakira.github.io/posts/2026/04/blog-post</id><content type="html" xml:base="https://alexisakira.github.io/posts/2026/04/blog-post-20/"><![CDATA[<p>In my <a href="https://alexisakira.github.io/posts/2025/08/blog-post-06/">post</a>, I mentioned that I have been happy with the <a href="https://i.capitalone.com/JoI8RuaOd">Capital One Quicksilver Card</a> because it offered 0% intro APR for 15 months (and the card has no annual fee and gives 1.5% cash back on all purchases).</p>

<p>During the 0% APR period, I racked up nearly $30,000 of credit card debt. By doing so, my credit score went down from around 835 to 795. However, I paid off the debt last week before the end of the 0% APR period. A few days later, my credit score went back to 835. Now that the 0% APR period is over and the credit card offers only 1.5% cash back on everything (less than 2% with my Fidelity card), I contacted Capital One to switch from Quicksilver to Savor, which offers 3% cash back on dining and bakeries.</p>

<p>I highly recommend the card to anybody. If you open an account by clicking this <a href="https://i.capitalone.com/JoI8RuaOd">link</a>, you will receive an extra sign-up bonus.</p>]]></content><author><name>Alexis Akira Toda</name><email>alexis.akira.toda(at)emory.edu</email></author><category term="credit card" /><category term="personal finance" /><summary type="html"><![CDATA[In my post, I mentioned that I have been happy with the Capital One Quicksilver Card because it offered 0% intro APR for 15 months (and the card has no annual fee and gives 1.5% cash back on all purchases). During the 0% APR period, I racked up nearly $30,000 of credit card debt. By doing so, my credit score went down from around 835 to 795. However, I paid off the debt last week before the end of the 0% APR period. A few days later, my credit score went back to 835. Now that the 0% APR period is over and the credit card offers only 1.5% cash back on everything (less than 2% with my Fidelity card), I contacted Capital One to switch from Quicksilver to Savor, which offers 3% cash back on dining and bakeries. I highly recommend the card to anybody. If you open an account by clicking this link, you will receive an extra sign-up bonus.]]></summary></entry><entry><title type="html">Crowded airport lounges</title><link href="https://alexisakira.github.io/posts/2026/04/blog-post-10/" rel="alternate" type="text/html" title="Crowded airport lounges" /><published>2026-04-10T00:00:00-07:00</published><updated>2026-04-10T00:00:00-07:00</updated><id>https://alexisakira.github.io/posts/2026/04/blog-post</id><content type="html" xml:base="https://alexisakira.github.io/posts/2026/04/blog-post-10/"><![CDATA[<p>I often visit airport lounges, and a common experience is that they are crowded.</p>

<p>It is easy to explain why airport lounges are crowded. The cause is the failure to apply the price mechanism. Any competent student of economics knows that prices are determined to equilibrate supply and demand. When you set the price above the equilibrium price, supply will exceed demand. That is why the minimum wage policy causes unemployment. When you set the price below the equilibrium price, demand will exceed supply. That is why rent control causes a housing shortage.</p>

<p>It is the same with airport lounges. The usual way to access airport lounges is to have a credit card that grants access. For instance, holders of the American Express Platinum card can enter Centurion lounges. Now, holding the credit card incurs an annual fee, a fixed cost. But once you have the right credit card, you can access the lounge for free, so the marginal cost is zero. Demand responds to marginal cost, not fixed (sunk) cost. That is why demand for airport lounges exceeds supply (space).</p>

<p>I often fly through the Atlanta airport, and when I have enough time, I mindlessly visit the Centurion lounge at Terminal E. These days, it is not uncommon to wait 30 minutes, so I usually use the American Express app to get on the waitlist while I am still on the plane train to reduce the wait time. The other day, I saw a customer at the entrance furiously shout, “If we need to wait that much, it’s not worth it anymore,” and left. If American Express decides to charge a small entry fee to the lounge, like $5 or $10, I bet the crowds will quickly disappear. But paying a small entry fee each time is not exactly luxurious. An alternative is to sell lounge memberships separately or limit access to this number of times per year, as Delta Airlines does with its Sky Club lounges.</p>]]></content><author><name>Alexis Akira Toda</name><email>alexis.akira.toda(at)emory.edu</email></author><category term="miscellaneous" /><category term="travel" /><summary type="html"><![CDATA[I often visit airport lounges, and a common experience is that they are crowded.]]></summary></entry><entry><title type="html">Income inequality at UCSD economics, 2024</title><link href="https://alexisakira.github.io/posts/2026/01/blog-post-14/" rel="alternate" type="text/html" title="Income inequality at UCSD economics, 2024" /><published>2026-01-14T00:00:00-08:00</published><updated>2026-01-14T00:00:00-08:00</updated><id>https://alexisakira.github.io/posts/2026/01/blog-post</id><content type="html" xml:base="https://alexisakira.github.io/posts/2026/01/blog-post-14/"><![CDATA[<p>The <a href="https://ucannualwage.ucop.edu/wage/">University of California compensation data</a> for 2024 is now published. I have updated the data set for <a href="https://alexisakira.github.io/publications/2019-EJW/">my paper</a> and rerun the regressions. For readers interested in predicting their salaries, the 2024 prediction equation is
\[\log y = 12.20 -0.0096T + 0.0051N_\textrm{pub} + 0.0201N_\textrm{top5} + 0.2181D_\textrm{tenure} + 0.2601D_\text{full}, \]
where \(y\) is the 9-month salary, \(T\) is the number of years elapsed since obtaining Ph.D., \(N_\textrm{pub}\) is the cumulative number of peer-reviewed research articles, \(N_\textrm{top5}\) is the cumulative number of top 5 publications, and \(D_\textrm{tenure}, D_\textrm{full}\) are dummy variables for tenure and full professor.</p>

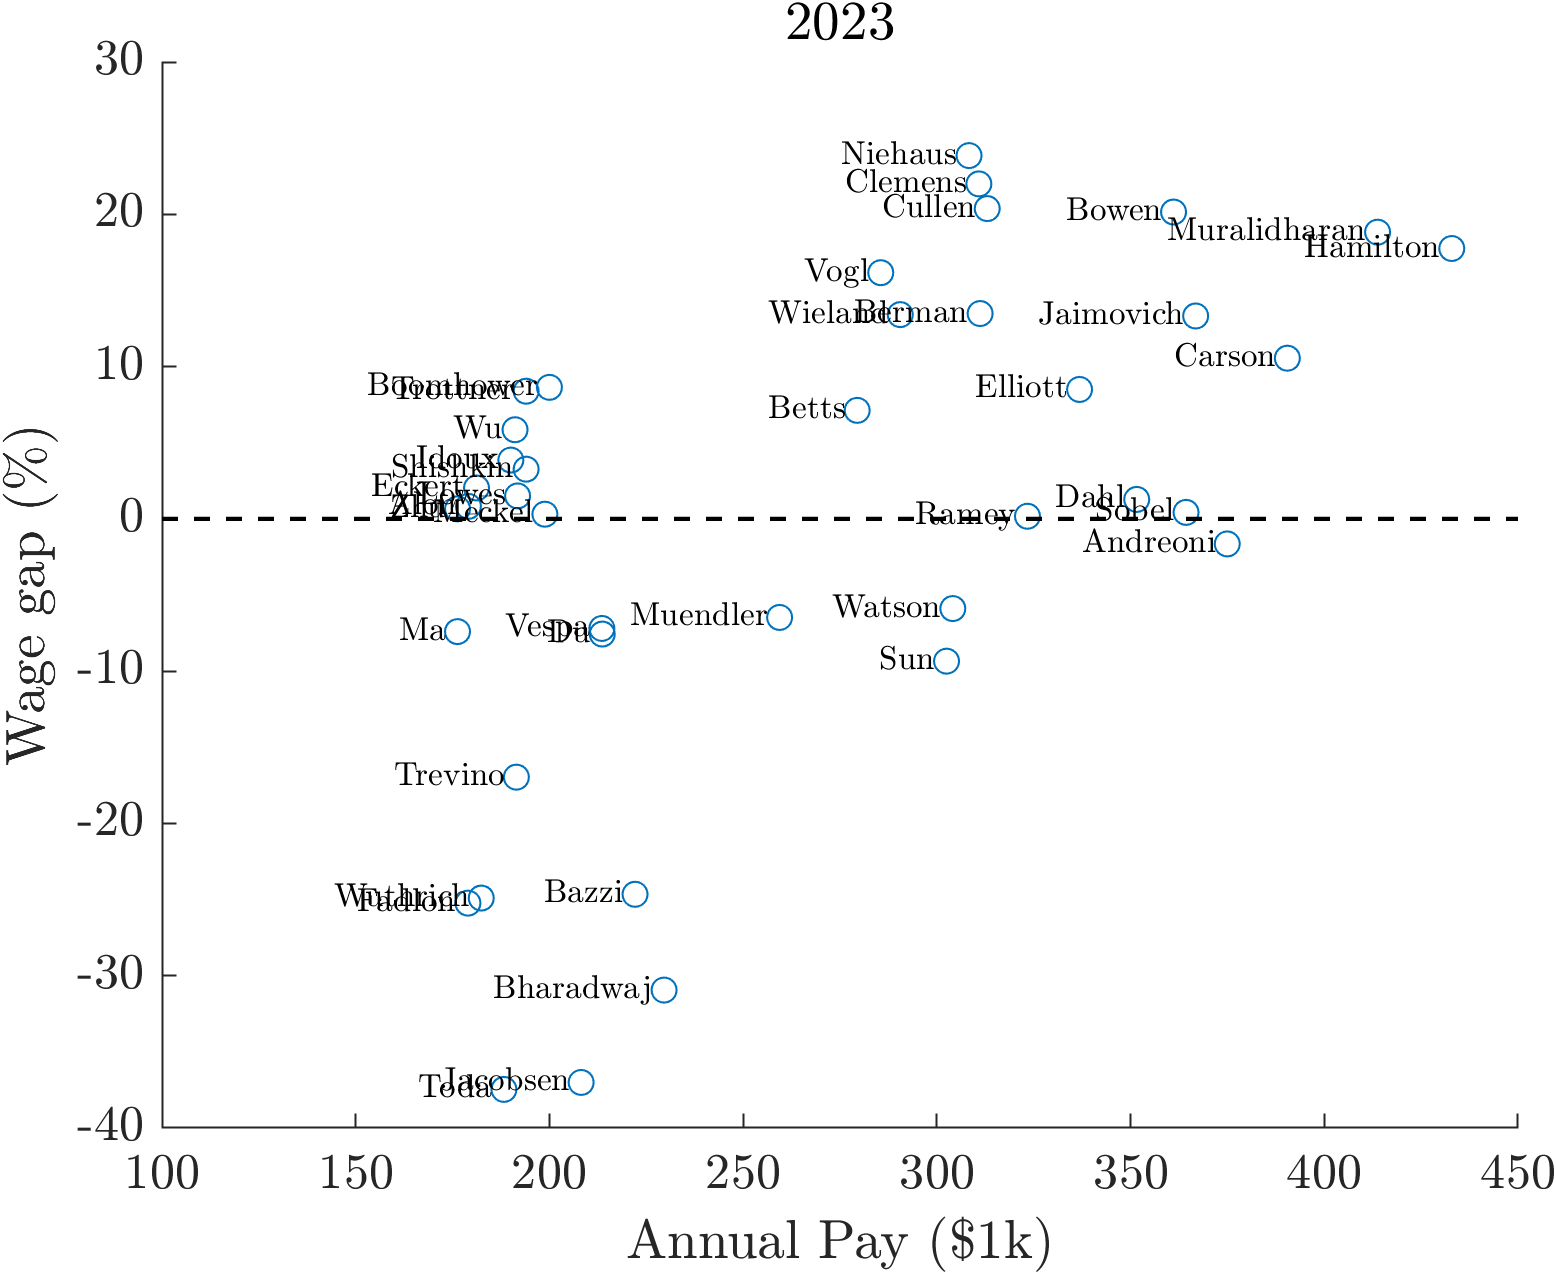
<p>For comparison, I show the scatter plots from both 2023 and 2024. Congratulations to Jeff Clemens and Paul Niehaus for their substantial raises, as was the case in 2023. Notably, two faculty members in the lower left—Kaspar Wuthrich and I—have left. (Kaspar moved to Michigan, another public university, so curious readers can compare his salary before and after the move.) If I were the department chair, I would focus on retaining faculty in the lower left.</p>

<p><img src="/assets/images/scatter_2023.png" alt="Wage gap in 2023" /></p>

<p><img src="/assets/images/scatter_2024.png" alt="Wage gap in 2024" /></p>]]></content><author><name>Alexis Akira Toda</name><email>alexis.akira.toda(at)emory.edu</email></author><category term="research" /><summary type="html"><![CDATA[The University of California compensation data for 2024 is now published. I have updated the data set for my paper and rerun the regressions. For readers interested in predicting their salaries, the 2024 prediction equation is \[\log y = 12.20 -0.0096T + 0.0051N_\textrm{pub} + 0.0201N_\textrm{top5} + 0.2181D_\textrm{tenure} + 0.2601D_\text{full}, \] where \(y\) is the 9-month salary, \(T\) is the number of years elapsed since obtaining Ph.D., \(N_\textrm{pub}\) is the cumulative number of peer-reviewed research articles, \(N_\textrm{top5}\) is the cumulative number of top 5 publications, and \(D_\textrm{tenure}, D_\textrm{full}\) are dummy variables for tenure and full professor.]]></summary></entry><entry><title type="html">My 2026 financial resolution</title><link href="https://alexisakira.github.io/posts/2026/01/blog-post-01/" rel="alternate" type="text/html" title="My 2026 financial resolution" /><published>2026-01-03T00:00:00-08:00</published><updated>2026-01-03T00:00:00-08:00</updated><id>https://alexisakira.github.io/posts/2026/01/blog-post</id><content type="html" xml:base="https://alexisakira.github.io/posts/2026/01/blog-post-01/"><![CDATA[<p>Here are my 2026 financial resolutions.</p>

<h2 id="contribute-to-ira-using-backdoor-roth">Contribute to IRA using backdoor Roth</h2>

<p>In 2026, the IRA contribution limit increased to $7,500 (from $7,000). I will max out both for my wife and me.</p>

<h2 id="contribute-to-hsa">Contribute to HSA</h2>

<p>In 2026, the HSA contribution limit (family) has increased to $8,750 (from $8,550). Since I have two HSAs (one for my workplace and one with Fidelity), I will wait to contribute the last few hundred dollars to Fidelity to avoid over-contributing (since my workplace HSA sometimes offers additional benefits).</p>

<h2 id="donate-stocks-with-capital-gains-to-my-kids-utma-accounts">Donate stocks with capital gains to my kids’ UTMA accounts</h2>

<p>Donating stocks lets me realize up to $1,350 in capital gains tax-free by using this loophole:</p>
<ul>
  <li>The annual gift tax exclusion limit is $19,000 ($38,000 for married couples filing jointly) (see <a href="https://www.irs.gov/faqs/interest-dividends-other-types-of-income/gifts-inheritances/gifts-inheritances-1">here</a>).</li>
  <li>Child’s unearned income above $2,700 is taxed at parent’s rate (see <a href="https://www.irs.gov/pub/irs-dft/i8615--dft.pdf">here</a>).</li>
  <li>Standard deduction for a dependent is $1,350 (see <a href="https://apps.irs.gov/app/vita/content/00/00_13_005.jsp">here</a>).</li>
</ul>

<p>Therefore, if the market value of the stocks I donate is less than $38,000 and capital gains are less than $1,350, the child does not need to pay any tax.</p>

<h2 id="use-529-funds-wisely">Use 529 funds wisely</h2>

<p>Since July 2025, the K-12 qualified expenses for 529 plans have significantly expanded (see <a href="https://www.savingforcollege.com/article/what-you-can-pay-for-with-a-529-plan">here</a>). I will keep track of my expenses in a spreadsheet.</p>

<h2 id="pay-off-credit-card-debt">Pay off credit card debt</h2>

<p>In 2025, my wife and I have racked up around $50,000 in credit card debt. This may sound insane, but actually, it was on purpose. We each opened the <a href="https://i.capitalone.com/JoI8RuaOd">Capital One Quicksilver card</a>, which offers 0% APR for 15 months and 1.5% cashback on all purchases. We used this card to pay taxes and purchase stuff for our bathroom remodeling project. I have been saving cash using Treasury bills (to avoid state income taxes), so we saved over a thousand dollars from the interest rate arbitrage. (However, my credit score declined from 840 to 790 by racking up credit card debt, though I don’t regret it.)</p>

<h2 id="downgrade-american-express-blue-cash-preferred-card">Downgrade American Express Blue Cash Preferred card</h2>

<p>In <a href="https://alexisakira.github.io/posts/2025/12/blog-post-28/">this post</a>, I mentioned that the <a href="https://www.ace.aaa.com/mktg/financial/daily-advantage.html">AAA Daily Advantage Visa Signature card</a> dominates the <a href="https://www.americanexpress.com/us/credit-cards/card/blue-cash-preferred/">American Express Blue Cash Preferred card</a> for groceries. I will downgrade the Amex card to one without an annual fee before the renewal date so that I can keep the long credit history (since 2010).</p>

<h2 id="use-credit-cards-optimally">Use credit cards optimally</h2>

<p>I will use my credit cards optimally.</p>

<ul>
  <li><a href="https://www.americanexpress.com/us/credit-cards/card/platinum/">American Express Platinum Card</a> for flight tickets booked directly with airline or through American Express Travel (5%) and prepaid hotels booked through American Express Travel (5%).</li>
  <li><a href="https://www.americanexpress.com/us/credit-cards/card/blue-cash-preferred/">American Express Blue Cash Preferred Card</a> for groceries (6%) and transit (train, bus, parking, rideshare, etc.; 3%).</li>
  <li><a href="https://www.costco.com/credit-card.html">Costco Anywhere Visa Card</a> for Costco gas (5%), other gas and EV charging (4%), and dining (3%).</li>
  <li><a href="https://www.ace.aaa.com/mktg/financial/daily-advantage.html">AAA Daily Advantage Visa Signature Card</a> for Costco (3%) and pharmacies (3%), and if I cancel the American Express Blue Cash Preferred card, then groceries (5%).</li>
  <li><a href="https://www.capitalone.com/credit-cards/quicksilver/">Capital One Quicksilver Card</a> for hotels, vacation rentals and rental cars booked through Capital One Travel (5%).</li>
  <li><a href="https://www.fidelity.com/spend-save/preapproval-visa-signature-card">Fidelity Rewards Visa Signature Card</a> for any purcahse (2%).</li>
</ul>]]></content><author><name>Alexis Akira Toda</name><email>alexis.akira.toda(at)emory.edu</email></author><category term="personal finance" /><summary type="html"><![CDATA[Here are my 2026 financial resolutions.]]></summary></entry><entry><title type="html">Credit card for grocery shopping</title><link href="https://alexisakira.github.io/posts/2025/12/blog-post-28/" rel="alternate" type="text/html" title="Credit card for grocery shopping" /><published>2025-12-28T00:00:00-08:00</published><updated>2025-12-28T00:00:00-08:00</updated><id>https://alexisakira.github.io/posts/2025/12/blog-post</id><content type="html" xml:base="https://alexisakira.github.io/posts/2025/12/blog-post-28/"><![CDATA[<p>One key principle for saving money is to cut costs in a category with a high share of expenditures.</p>

<p>Grocery shopping is one of them for me. Since 2010, I have been using the <a href="https://www.americanexpress.com/us/credit-cards/card/blue-cash-preferred/">American Express Blue Cash Preferred card</a>, which I recently discussed in <a href="https://alexisakira.github.io/posts/2025/12/blog-post-06/">this post</a>. Just to recap, the annual fee is $95, and the cashback rate on groceries is 6% up to $6,000 in purchases, after which it drops to 1%.</p>

<p>I asked Gemini for some good grocery shopping cards. Not surprisingly, the Amex Blue Cash Preferred card came on top, but there were a few others. One of them, the <a href="https://www.ace.aaa.com/mktg/financial/daily-advantage.html">AAA Daily Advantage Visa Signature card</a>, drew my attention. There is no annual fee, and the cashback rate on groceries is 5% up to $10,000 spent.</p>

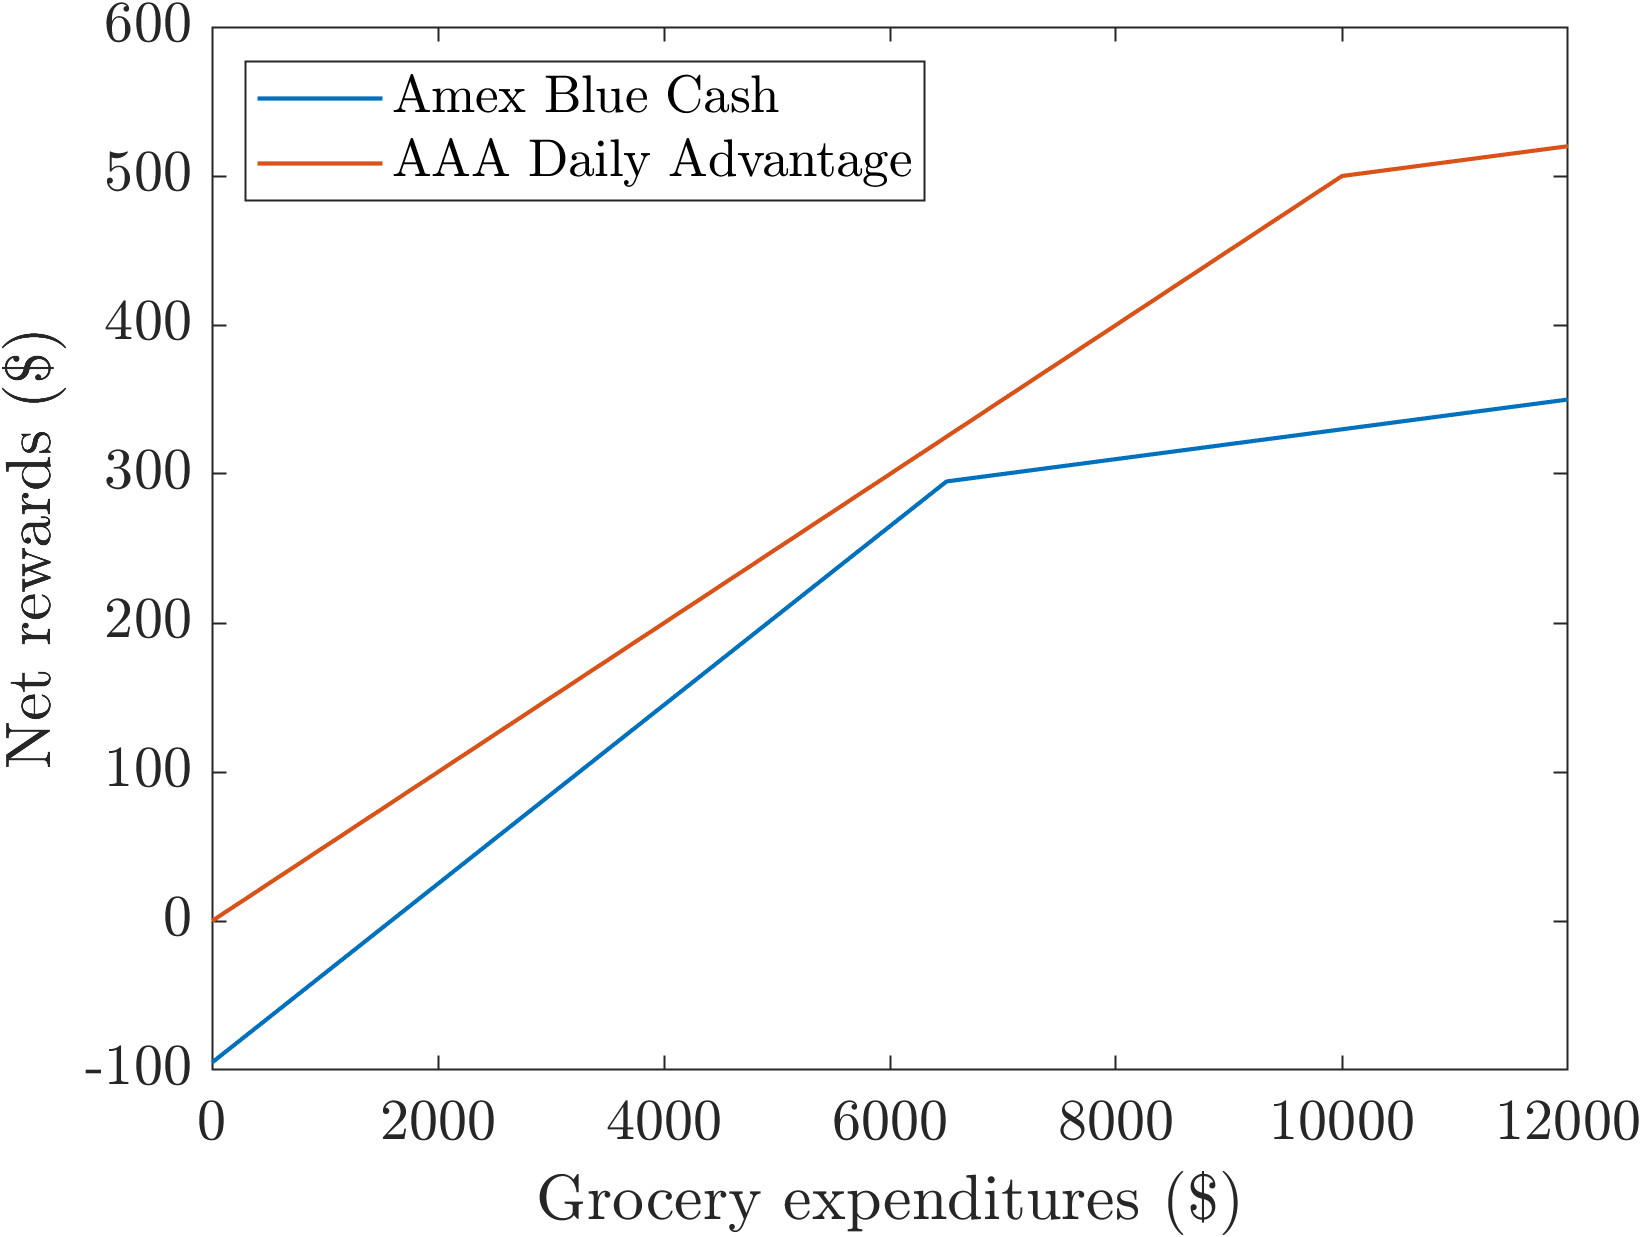
<p>The AAA Daily Advantage card’s rewards surpass those of the Amex Blue Cash card (net of annual fee), as shown below. Let \(x\) represent grocery expenditure. Ignoring the accelerated earnings cap ($6,000 for Amex, $10,000 for AAA), the break-even point satisfies:
\[\frac{6}{100}x-95=\frac{5}{100}x\iff x=9500.\]
Since the break-even point is above the cap for Amex ($6,000) and the cashback rate of AAA weakly dominates Amex beyond $6,000, it follows that AAA always dominates Amex.</p>

<p><img src="/assets/images/AmexAAA.png" alt="Rewards on Amex and AAA cards" /></p>

<p>Does this mean I should ditch the Amex card? Not so fast. If we look at the benefit structure of the AAA card, there is also a 3% cashback on wholesale club spending, including Costco, but the accelerated cashback rate applies only to the first $10,000 spent. Recalling that the cashback rate on the Costco Anywhere Visa card is 2% (see <a href="https://alexisakira.github.io/posts/2025/12/blog-post-25/">here</a>), and that my annual household expenditure on Costco is about $10,000, it is better to reserve the AAA card for Costco instead of other grocery spending. Of course, if my wife also opens an AAA card, then we can just use two AAA cards to cover our entire Costco and grocery spending without hitting the combined $20,000 cap. I will first experiment with the AAA card (which I applied for just yesterday) and see how it goes.</p>]]></content><author><name>Alexis Akira Toda</name><email>alexis.akira.toda(at)emory.edu</email></author><category term="credit card" /><category term="personal finance" /><summary type="html"><![CDATA[One key principle for saving money is to cut costs in a category with a high share of expenditures.]]></summary></entry></feed>